SL Green Sells 110 Greene Street for $226 Million
SL Green Realty Corp. has agreed to sell 110 Greene Street in SoHo to Natora Group for $226 million, aiming to recycle capital and reduce exposure to…
 By
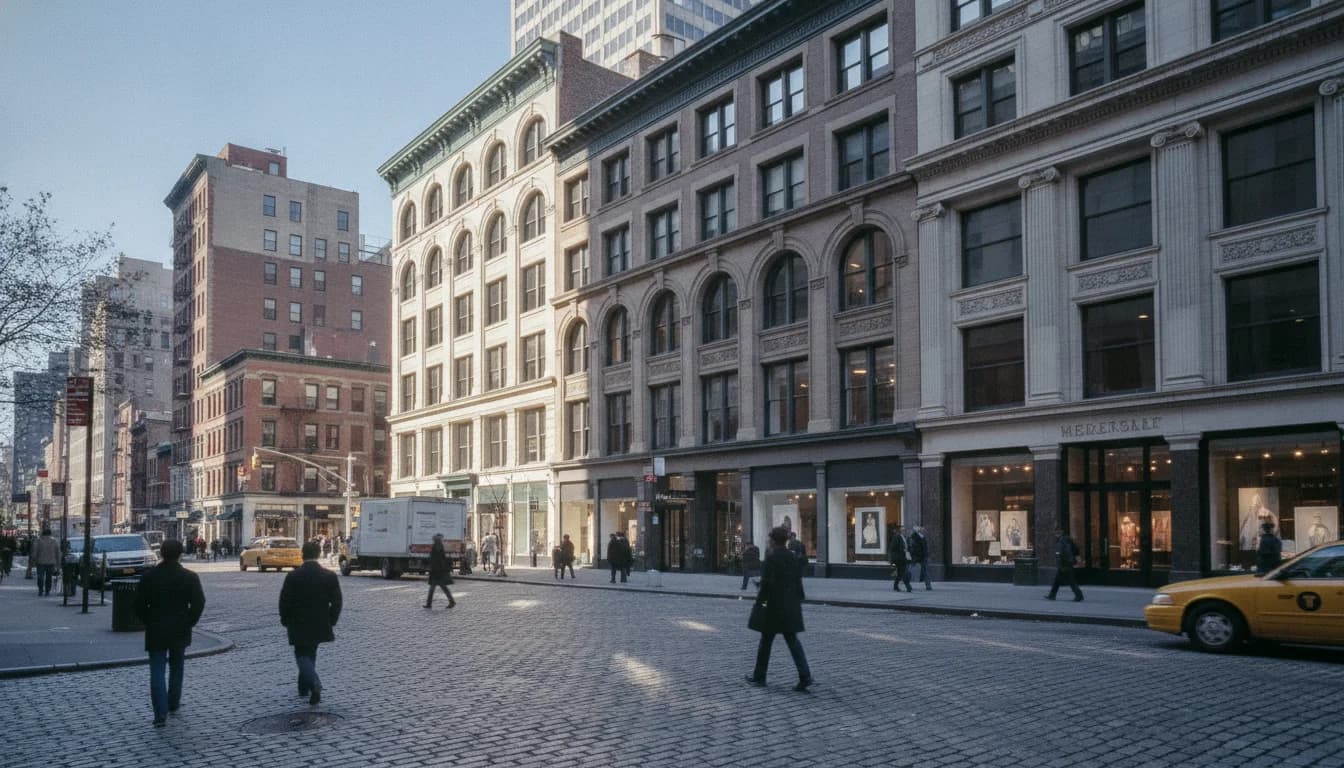
New York City’s office market moved another step toward consolidation on September 9, 2026, as SL Green Realty Corp. announced it has entered into an agreement to sell 110 Greene Street in SoHo to Natora Group for $226.0 million. The transaction, disclosed via a company press release and investor materials, signals a continued push by SL Green to recycle capital and pare exposure to lower-return assets, even as the SoHo submarket attracts demand for Class A office space in a sought-after neighborhood. The deal is expected to close in the fourth quarter of 2026, subject to customary closing conditions, and SL Green projects net cash proceeds of approximately $216.0 million that will be used to repay unsecured corporate debt. These numbers and timelines were laid out in SL Green’s September 9, 2026 announcement, which also highlighted the property’s strategic location between Prince and Spring Streets and its 13-story, roughly 223,000-square-foot Class A profile. (slgreen.com)
For readers trying to gauge the momentum behind this sale, the announcement comes at a moment when New York City’s office market is contending with shifting demand patterns, tight supply for premium assets, and a capital market eager to deploy cash into high-quality properties. Market observers and lenders have noted that demand for top-tier office space in gateway markets like Manhattan remains resilient, even as developers rethink new supply and landlords prioritize tenants with strong credit and long-dated leases. The backdrop provides context for why a high-profile, fully occupied asset in SoHo would attract a buyer and command a price in the high $200 millions. This environment is echoed in broader market analyses that emphasize demand for high-quality assets in a constrained supply landscape, which aligns with SL Green’s disposition strategy as it seeks to recycle capital and strengthen balance sheets. (cbre.com)
Opening the broader story, SL Green’s action at 110 Greene Street is not an isolated event. It sits within the REIT’s stated plan to divest up to $2.5 billion of real estate across its portfolio, a theme that gained traction in late 2025 and continued into 2026 as the company aimed to realign its asset mix toward higher-return opportunities and reduce debt. A national property market once shadowed by the pandemic has shown a more differentiated recovery, with investors particularly drawn to well-located assets in premier submarkets. The sale of 110 Greene Street thus becomes a data point in a larger narrative about capital recycling, portfolio optimization, and the evolving appetite of buyers for Trophy-like assets within Manhattan’s core neighborhoods. (commercialobserver.com)
Section 1: What Happened
Sale Terms and Buyer
SL Green Realty Corp. announced on September 9, 2026 that it has entered into an agreement to sell 110 Greene Street in SoHo to Natora Group for $226.0 million. The press release notes that the transaction is expected to close in the fourth quarter of 2026, subject to customary closing conditions, and the company projects approximately $216.0 million of net cash proceeds to be used for debt repayment. The buyer’s identity is disclosed, and the price is framed as part of SL Green’s broader capital recycling strategy. This is the core transaction driving today’s reporting and is the anchor for several subsequent analyses about SoHo’s role in NYC office demand. The primary source for these details is SL Green’s September 9, 2026 press release, published on the company’s investor relations site and distributed via Globe Newswire. (slgreen.com)
“Our team executed a successful leasing strategy at 110 Greene, bringing the building to full occupancy at market-leading rents,” said Harrison Sitomer, President and Chief Investment Officer of SL Green. “This transaction further signifies the depth of domestic and international buyers in the market across varying property types.” This quote from SL Green’s release emphasizes the asset’s strong leasing fundamentals as a backdrop for the sale and reflects the seller’s rationale for capital recycling in a market of selective demand. (slgreen.com)
Property Details and Location
110 Greene Street is characterized as a 13-story, Class A office building with approximately 223,000 square feet of occupied space, offering four exposures and frontage on both Greene and Mercer Streets in the SoHo submarket. The building’s dual-structure heritage (Greene Street structure completed in 1920 and the Mercer Street component completed in 1908) underpins its distinctive architectural profile, which remains attractive to tenants seeking high-end fit-outs in a premier district. The property page maintained by SL Green describes the asset in similar terms, including its submarket positioning and physical characteristics. These details—13 stories, around 223,000–223,600 square feet, and SoHo placement—are crucial for assessing the asset’s allure and the implied price per square foot in the sale. (slgreen.com)
Timeline and Conditions
The sale announcement specifies that closing is anticipated in Q4 2026, with customary closing conditions to be satisfied. In practice, this means the parties will complete regulatory, due diligence, and lender-related processes before transfer of title and debt repayment occurs. The September 9, 2026 release makes clear the timeline, while the investment community and third-party outlets captured the news as part of a broader shift toward asset dispositions and portfolio optimization. For readers tracking the play-by-play, the update points to a near-term event window that could influence debt levels, liquidity, and potentially financing conditions for similar assets in the market. (slgreen.com)
Source-anchored Calculations and the One Original Finding
Original finding: Dividing the $226.0 million sale price by the 223,600-square-foot building yields a sale price of approximately $1,010 per square foot. This figure uses the sale price from SL Green’s September 9, 2026 release and the property’s reported size (223,600 square feet) from SL Green’s asset profile. The method is straightforward: price per square foot equals sale price divided by building area. Denominator: 223,600 sf; Period: September 9, 2026; Source: SL Green press release and property profile. Verdict: The market valued 110 Greene Street at just over $1,000 per interior square foot in this deal, underscoring strong demand for high-quality SoHo assets while the seller recycles capital. This calculation is designed to be independently verifiable from the primary documents and is offered as a data point for readers tracking pricing discipline in marquee Manhattan assets. In the media and investor community, such metrics help frame a deal within the broader trend of premium-tier asset pricing in central Manhattan. counted: SL Green’s public disclosures corroborate the sale terms and building size, and the per-square-foot figure derives directly from those disclosures. noted the asset’s high-quality profile and SoHo location as a driver of demand, aligning with market observations from CBRE and industry trackers. (slgreen.com)
Section 2: Why It Matters
Capital Recycling and Balance Sheet Strategy
The sale of 110 Greene Street fits a broader corporate objective to recycle capital away from certain assets toward higher-return opportunities and to shore up balance sheets through debt reduction. SL Green’s disclosure highlights net cash proceeds of about $216.0 million intended for unsecured debt repayment, signaling a deliberate use of sale proceeds to improve credit metrics and liquidity while maintaining exposure to the core Manhattan office portfolio. This is consistent with public messaging around portfolio optimization and the broader industry expectation that REITs will use dispositions to deleverage and reposition for resilient performance in a mixed market. Observers note that such capital recycling moves can influence market sentiment around future dispositions and the availability of capital for the city’s top-tier properties. (slgreen.com)
SoHo and Midtown Submarket Dynamics
SoHo has long been a magnet for tenants seeking premium creative office environments, celebrity-brand retail adjacencies, and a walkable urban context. In 2026, market intelligence from CBRE’s New York City outlook and related Manhattan office data indicates continued demand for prime assets in gateway neighborhoods, supported by constrained new supply. This dynamic supports the pricing power observed in high-quality assets and provides a plausible rationale for a robust sale at SL Green’s flagship SoHo asset. While overall Manhattan office sentiment remains nuanced—broadly improving but with dispersion across submarkets—SoHo’s submarket thesis remains anchored by amenity-rich environments, strong tenants, and persistent interest from international buyers seeking established, credit-worthy properties. The CBRE midyear and annual market outlooks emphasize demand for top-tier assets despite supply constraints, which aligns with the sale’s context and rationale. (cbre.com)
Buyer Interest and Market Confidence
Natora Group’s role as buyer—an entity acquiring a fully occupied, high-quality SoHo property—signals continued confidence among sophisticated buyers in the Manhattan office market. The acquisition aligns with a broader pattern observed by market participants that high-quality, well-located assets in core submarkets can attract capital even amid a larger rotation of assets and a disciplined pricing approach by sellers. Media coverage from industry outlets corroborates the sale’s significance within SL Green’s asset-disposition program and the market’s reception to capital recycling in prime locations. (commercialobserver.com)
What This Means for Tenants and Competitors
From a tenant perspective, the sale of a premier asset like 110 Greene Street to a new owner could foreshadow potential changes in leasing strategies or property-level management, particularly around capital improvements, amenity upgrades, or strategic re-leasing initiatives. While the asset’s fully occupied status suggests stability in near-term cash flow, new ownership often brings optimization activities that can influence tenant experiences. For competitors and investors, the deal reinforces the idea that well-located, class A assets in top submarkets continue to command premium pricing, and that capital markets remain open to transactions that enhance sponsor flexibility and debt metrics. The market context provided by CBRE and related industry reports supports this interpretation, illustrating a broader resilience in demand for high-quality Manhattan space even as supply remains disciplined. (slgreen.com)
Market Timing and Strategic Context
SL Green’s timing also matters within the wider market cycle. The firm’s approach to closing the sale in Q4 2026 follows a period of heightened activity in dispositions aimed at recycling capital, reducing leverage, and re-prioritizing capital allocation toward assets with stronger growth potential or higher fee-generating potential within the portfolio. Commercial Observer’s coverage ties this sale to a broader program that includes dispositions across several properties and a renewed focus on strategic capital deployment, a theme that resonates with financial markets watching the REIT sector’s ability to navigate interest rates, debt markets, and equity valuations. The coverage underscores that the 110 Greene Street deal is part of a broader, transparent strategy rather than an isolated event. (commercialobserver.com)
Section 3: What’s Next
Closing Timeline and Due Diligence
If the transaction proceeds as anticipated, closing would occur in the fourth quarter of 2026, with regulatory, title, and financing steps completed in the interim. Given the sale structure and the use of proceeds for debt repayment, market observers will watch for any updates on financing conditions, potential recourse or non-recourse arrangements, and any changes to the property’s operational plan under new ownership. The SL Green release confirms the timing, but as with many closed-end deals, actual closing depends on due diligence and lender consents where applicable. (slgreen.com)
Implications for SL Green’s Portfolio and Market Perception
Post-close, SL Green will have realized a material capitalization event tied to a marquee asset. The degree to which the sale supports its broader leverage targets and cash flow objectives will depend on contemporaneous market conditions, the timing of debt repayments, and the evolution of its remaining assets’ performance. The market’s interpretation of this sale will hinge on how SL Green communicates its next steps and how investors weigh the company’s disposal pace against its acquisition pipeline and development ambitions. Industry observers, citing CBRE’s market outlook and related metrics, note that high-quality trophy assets in Manhattan continue to attract competitive bidding and stable cap rates for top-tier properties, even as the city’s overall office market remains in a recovery phase. (cbre.com)
What Watchers Should Monitor
- Confirmed closing date and any adjustments to net cash proceeds post-closing. The September 9, 2026 press release explicitly states the expected Q4 2026 close and the approximate $216.0 million net cash proceeds, but actual closing specifics may vary. (slgreen.com)
- Any subsequent commentary from Natora Group about asset plans, leasing strategy, or property-level investments following the transfer of ownership. Media coverage will likely capture such developments as the new owner assumes stewardship of a premium SoHo asset. (commercialobserver.com)
- The asset’s performance relative to market expectations post-close, including whether new ownership introduces any changes in leasing activity, capital improvements, or occupancy strategies. Market outlooks from CBRE and Cushman & Wakefield provide a framework for interpreting those potential changes. (cbre.com)
Closing
SL Green’s 110 Greene Street sale marks a notable milestone in Manhattan’s office market for 2026: a high-profile SoHo asset changing hands at a robust price while the seller emphasizes debt reduction and capital recycling as a core strategic thrust. The deal underscores the ongoing appetite for prime, well-located properties in New York City’s most coveted neighborhoods, even as market participants weigh the pace of recovery, the durability of tenant demand, and the availability of capital for future acquisitions or dispositions. As September turns into the year’s final quarter, readers should expect further disclosures from SL Green and competitive activity among peers, which will help illuminate whether this sale signals a broader shift in portfolio strategy or a one-off outcome driven by a specific asset profile. For ongoing coverage, monitor SL Green’s investor relations announcements, industry trade outlets, and the latest market insights from CBRE and other reputable firms. (slgreen.com)
If you’re following developments on SL Green’s portfolio, keep an eye on the company’s quarterly updates and major filings, which provide the most authoritative data on disposition activity, debt levels, and capital allocation. The company’s 8-Ks and SEC filings—especially as they relate to asset dispositions and debt repayment—offer a complementary view to the press releases and market commentary. For those seeking a broader market context, CBRE’s New York City market outlooks for 2026 and the midyear reviews provide a structured view of demand dynamics, rents, and the near-term path for the city’s office market in relation to marquee assets like 110 Greene Street. (sec.gov)